
CoreWeave, a "neocloud" that rents out Nvidia GPUs to AI companies, reported third quarter 2026 results on November 10. Revenue rose 168% from a year earlier, and the company raised its 2026 guidance. It still posted a net loss of $709 million, and its interest bill keeps growing.
The results came after a hard month for the stock. CNBC reported: "CoreWeave has lost over 40% of its value in the past month, as investors rotate out of companies most closely tied to AI infrastructure." We covered the credit stress around CoreWeave before these earnings and the October drop in CoreWeave and Nebius shares.
CoreWeave Q3 2026 results in numbers
For the quarter ended September 30, 2026, CoreWeave reported:
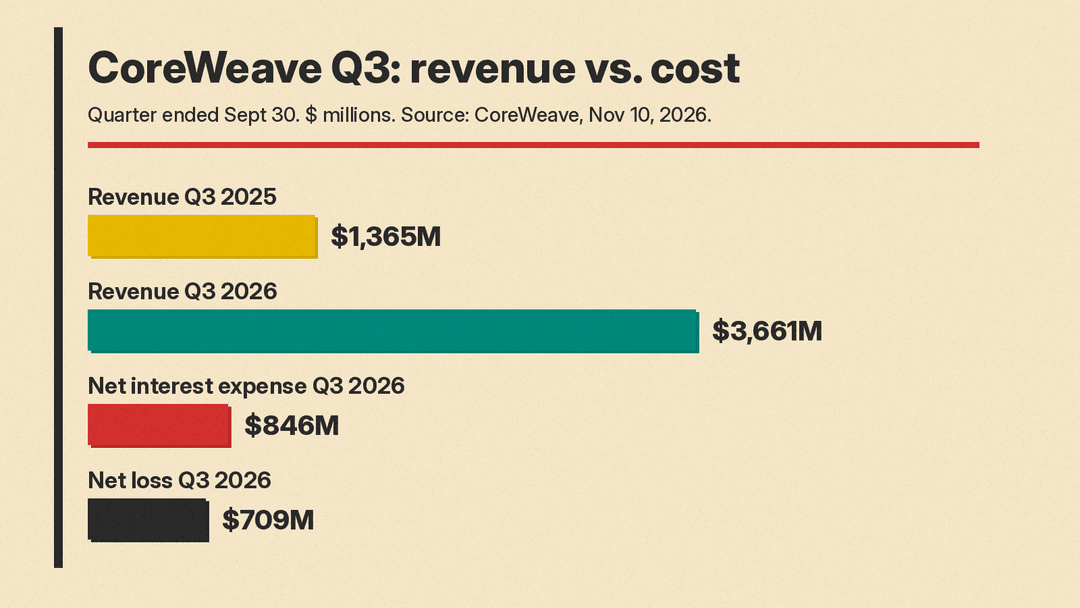
- Revenue: $3,661 million, up from $1,365 million a year earlier.
- Operating income: $207 million, up from $52 million.
- Net interest expense: $846 million, up from $310 million.
- Net loss: $709 million, or $1.27 per share, compared with $110 million a year earlier.
- Adjusted EBITDA: $2,256 million, a 62% margin.
- Adjusted operating income: $379 million.
- Revenue backlog: approximately $132.5 billion.
Revenue backlog is money CoreWeave expects to book later under customer contracts already signed. The company defines it as remaining performance obligations plus other amounts it estimates will be recognized as revenue under committed customer contracts. CNBC says backlog was $104 billion as of June.
Against LSEG consensus, per CNBC, the adjusted loss was 95 cents per share versus $1.16 expected, and revenue was $3.66 billion versus $3.55 billion expected.
CEO Michael Intrator said in the release: "This was a breakout quarter for CoreWeave, with revenue increasing by more than $1 billion sequentially and adjusted operating margins reaching double digits a quarter ahead of plan."
CoreWeave raises 2026 guidance
CoreWeave's business outlook now calls for:
- 2026 revenue of $13.0 billion to $13.3 billion.
- 2026 adjusted operating income of $1.275 billion to $1.375 billion, which the company calls "a 26% increase at the midpoint compared with our prior guidance."
- 2026 capital expenditures of $37 billion to $39 billion, raising the low end of the prior $35 billion to $39 billion range.
- Q4 2026 interest expense of $1.05 billion to $1.15 billion.
- Annualized run-rate revenue of $20 billion to $21 billion to exit 2026.
The company said the capex change is "a result of our expectation to deploy infrastructure and deliver it to customers sooner than planned."
In August, CNBC notes, guidance was $12.4 billion to $13.2 billion in revenue and $960 million to $1.15 billion in adjusted operating income. Analysts polled by LSEG had expected $12.86 billion in 2026 revenue.
Power, chips and customers
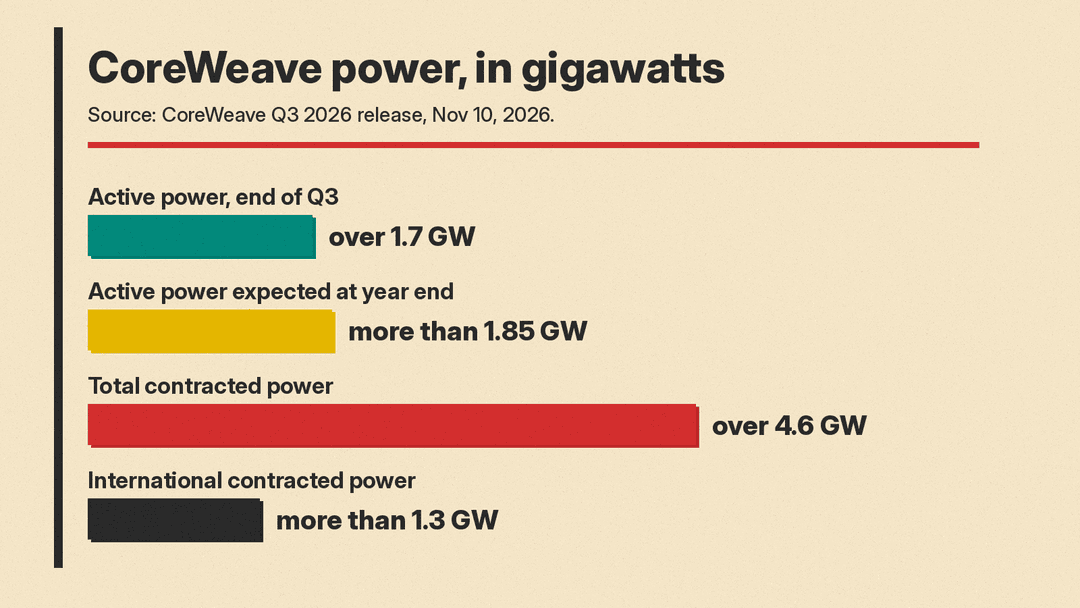
In the quarter, CoreWeave said it added more than 200 MW of active power to reach over 1.7 GW, doubling its active footprint since the start of the year. Total contracted power grew more than 900 MW to over 4.6 GW. More than 1.3 GW of contracted power is international, including India, Indonesia, and Spain. The company still expects more than 1.85 GW of active power at year end.
On hardware, CoreWeave said it brought online multi-rack Nvidia Vera Rubin NVL72 systems. It said the first production workloads, for Cognition, achieved 4.8x greater token throughput than GB200 NVL72. That is a company figure.
It also launched CoreWeave Forge, an AI development environment that brings together training, inference, evaluation and agent development workflows. Customer wins named include Canva, Substack and Wayve. Existing customers that expanded include OpenAI, Perplexity, Cohere and Jane Street.
How CoreWeave plans to pay for growth
CNBC reports that CoreWeave owed almost $47 billion in debt at the end of the quarter, and that some of its bond yields recently topped 16%. Reuters, via US News, says quarterly capital spending jumped to $14.5 billion from $9.4 billion in the prior quarter.
In the quarter, the company raised approximately $4.2 billion in convertible senior notes, set up an at-the-market equity program for up to 35 million Class A shares, and closed a $2.6 billion DDTL 5.5 Facility. Intrator also pointed to "approximately $9 billion in customer prepayments and deposits expected in the next three months alone."
On the call, Intrator said CoreWeave will get most of the capital it needs for 2027 through client prepayments and financing from hardware partners, and will raise "a limited amount" as well, per CNBC. Finance chief Nitin Agrawal said: "At current yields, we do not intend to issue additional parent-level unsecured debt through 2027." He projects under $5 billion in parent-level debt financing through 2027. On Nov. 11, Bloomberg reported that CoreWeave plans an investment-grade loan of at least $4 billion.
Reuters reports that CoreWeave said it would become profitable on an adjusted basis in the first half of 2028.
Agrawal added: "Should we choose to focus only on our committed backlog, we would expect capex for 2027 to remain in line with our 2026 capex investment, while revenue and EBITDA grow significantly."
Data center politics
CNBC notes that in the prior week, US voters rejected dozens of initiatives on data center development. Intrator said: "So to begin with, we do not anticipate any impact from the seismic regulatory shift that's occurred." He said almost all of CoreWeave's power is online or permitted and under construction.
He also said: "If data center construction across the sector were to slow, installed compute becomes scarcer, and the knock-on effect is that GPU pricing may stay higher for longer." And: "We could sell all of the capacity that we have to current buyers that are in the queue. We are choosing not to."
What analysts said
After the report, CNBC collected analyst notes. Morgan Stanley rates the stock Equal weight with a $70 target. UBS rates it Buy at $105, JPMorgan Overweight at $125, and Citi Buy at $128. Bernstein rates it Underperform with a $54 target and wrote: "Execution keeps improving. The fundamentals remain the overhang." Citi wrote: "Overall, the results show CoreWeave continues to execute on the controllables and support our view that the AI compute demand environment remains unquestionably strong."
Fellow neocloud Nebius is scheduled to report on Thursday, November 12, according to CNBC.
Why it matters
CoreWeave's report puts growth and cost figures side by side. Demand figures went up: revenue grew 168%, backlog reached about $132.5 billion, and 2026 guidance rose. Costs went up too: net interest expense was $846 million for the quarter, the net loss was $709 million, and CNBC puts debt at almost $47 billion. Management says client prepayments and financing from hardware partners will cover most of its 2027 capital needs.
Sources
- CoreWeave: CoreWeave Reports Strong Third Quarter 2026 Results (Nov 10, 2026)
- CNBC: CoreWeave beats on revenue and lifts guidance (Nov 10, 2026)
- CNBC: CoreWeave Q3 earnings lift stock, analysts stay cautious (Nov 11, 2026)
- Reuters via US News: CoreWeave Targets 2028 Profitability as AI Demand Surges (Nov 10, 2026)
