
CoreWeave is preparing to raise at least $4 billion through an investment-grade loan facility, Bloomberg reported, per Investing.com on November 11, 2026. Bloomberg cited people with knowledge of the matter, FourWeekMBA notes. The plan follows CoreWeave's Q3 results on November 10, when it raised its 2026 revenue outlook.
The headline number is the price. Early pricing talks point to a yield of 7% to 7.5%, Bloomberg reported, which Investing.com describes as "roughly half the prevailing yield on the company's existing high-yield debt." CoreWeave's quarterly interest bill has grown fast, so the rate it pays on new debt matters.
What Bloomberg reported
According to the Investing.com summary of the Bloomberg report:
- Size: at least $4 billion, through an investment-grade loan facility.
- Banks: led by Morgan Stanley and Mitsubishi UFJ Financial Group (MUFG).
- Timing: the loan "would be syndicated in phases and could launch as early as next week, though terms remain subject to change."
- Price: "Early pricing discussions point to an anticipated yield between 7% and 7.5%."
- Structure: CoreWeave "is structuring the facility around its computing hardware and underlying customer commitments, mirroring an $8.5 billion investment-grade transaction completed in March."
Investing.com also notes that on Tuesday, November 10, CoreWeave raised its full-year revenue outlook to between $13 billion and $13.3 billion, above what it calls Wall Street's $12.9 billion consensus.
Investment grade vs junk, in plain words
Rating agencies such as Moody's and S&P grade how likely a borrower is to repay. Investment grade is the safer tier, so lenders accept a lower rate. High yield, also called junk, is the riskier tier, so lenders ask for more.
CoreWeave sits on both sides of that line. Investing.com calls it a "junk-rated firm." In March, Moody's rated CoreWeave, Inc. Ba3, a junk grade, while it rated a CoreWeave loan secured by equipment and one customer contract A3, an investment grade.
The loan type matters too. A delayed draw term loan, or DDTL, is committed up front and drawn in stages, as the borrower buys and installs equipment.
How the March $8.5 billion loan worked
The March deal is the model Bloomberg points to, per Investing.com. On March 31, 2026, CoreWeave said it closed an $8.5 billion delayed draw term loan, the "DDTL 4.0 Facility." In that release:
- Ratings: A3 from Moody's and A (low) from DBRS, which CoreWeave called "the first investment-grade rated financing secured by HPC infrastructure and an associated customer contract."
- Recourse: CoreWeave described it as non-recourse.
- Pricing: a floating rate tranche at SOFR + 2.25% and a fixed rate tranche at approximately 5.9%.
- Term and collateral: it matures in March 2032 and is secured by substantially all assets of CoreWeave Compute Acquisition Co. VIII, LLC.
- Banks: MUFG and Morgan Stanley were co-structuring agents and joint bookrunners, the same two banks Bloomberg names now.
Moody's said the proceeds finance GPU infrastructure for a six year Master Services Agreement with Meta. Under it, CoreWeave will supply NVIDIA GB300 NVL72 servers at three sites in Virginia, North Dakota, and Georgia. Moody's said the A3 rating "reflects the Borrower's highly predictable revenue profile, underpinned by a long term, fixed payment take or pay MSA with Meta." It added that the fixed payments are independent of usage and the contract cannot be terminated for convenience.
What CoreWeave said on its earnings call
On the November 10 call, finance chief Nitin Agrawal described the plan in advance, as quoted by FourWeekMBA. He said CoreWeave has "two fundamentally different types of debt sitting on our balance sheet." One sits at the asset level, "directly financing our customer contracts backed by committed cash flow and cloud infrastructure." The other sits at the parent company.
He also said: "we expect to launch our next DDTL in the coming weeks. This will be an investment-grade facility with multiple rating agencies indicating a high investment-grade rating." He said it should price at a spread implying "a 7% to 7.5% yield based on current SOFR," and would finance more than 90% of the associated capital spending.
FourWeekMBA adds that Bloomberg did not say, in the part FourWeekMBA could read, whether the $4 billion is the facility Agrawal described.
Agrawal also said on the call, per CNBC: "At current yields, we do not intend to issue additional parent-level unsecured debt through 2027."
The yield gap in numbers
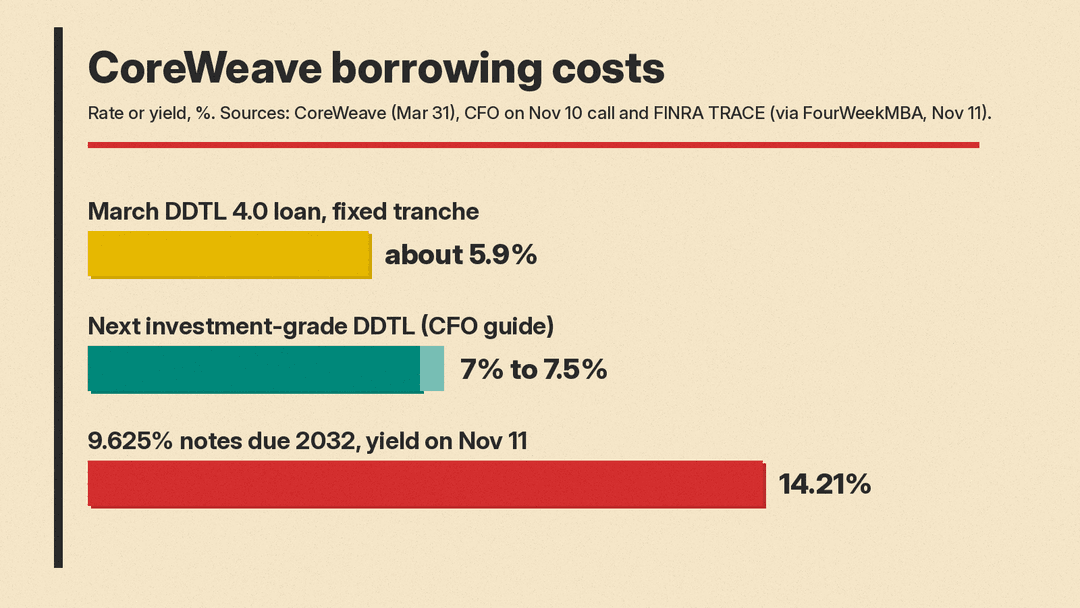
- March DDTL 4.0 fixed tranche: approximately 5.9%, per CoreWeave.
- Next investment-grade DDTL: 7% to 7.5% yield, as guided by Agrawal.
- CoreWeave's 9.625% notes due July 2032: last traded at 82.50 on November 11, a 14.21% yield, per FINRA TRACE data read by FourWeekMBA. FourWeekMBA puts the four fixed-rate note lines at yields of 14.21% to 15.14% at their last trades, and says FINRA data shows B1 from Moody's and B from S&P on the 2032 notes.
Why it matters
CoreWeave's own figures show why cheaper debt matters to it. In Q3, CoreWeave reported net interest expense of $846 million and a net loss of $709 million. It guided Q4 2026 interest expense to $1.05 billion to $1.15 billion and 2026 capital expenditures to $37 billion to $39 billion. CNBC reports that CoreWeave owed almost $47 billion in debt at the end of the quarter.
We covered the credit stress around CoreWeave before these earnings, when its bond yields were climbing. Bloomberg reported, per Investing.com, that the new loan is built around hardware and customer commitments, like the March deal. The 14% yields are on CoreWeave's own fixed-rate notes.
The terms are not final. Bloomberg reported, per Investing.com, that the deal could launch as early as next week and that terms remain subject to change.
Sources
- Investing.com: CoreWeave plans $4 billion high-grade loan, Bloomberg reports (Nov 11, 2026)
- FourWeekMBA: CoreWeave Plans $4B Investment-Grade Loan; Bonds Yield 14%+ (Nov 11, 2026)
- CoreWeave: CoreWeave Closes Landmark $8.5 Billion Financing Facility (Mar 31, 2026)
- Moody's: Moody's Ratings assigns A3 to CoreWeave Compute Acquisition Co. VIII, LLC (Mar 31, 2026)
- CoreWeave: CoreWeave Reports Strong Third Quarter 2026 Results (Nov 10, 2026)
- CNBC: CoreWeave Q3 earnings report (Nov 10, 2026)
