
Anthropic made its IPO filing public on Monday, October 26, 2026. The Hacker News thread on the S-1 had passed 1,500 points and 1,500 comments by late October 26 Pacific time, and summaries of the filing spread across X the same day. The filing says Anthropic has applied to list its Class A stock on the Nasdaq Global Select Market under the symbol "ANT." The price range is still blank.
This roundup collects what people said in the first day: the fight over the headline loss, the size of the compute bill, doubts about the valuation, the long list of risk factors, and the governance structure. For the filing itself, read our Anthropic S-1 explainer.

The $80.7 billion loss: real, but mostly on paper
The first number most people shared was the loss, which we also covered in our report on the leaked S-1 draft. The Kobeissi Letter's summary led with it: "Anthropic posted H1 2026 revenue of $16.3 billion with a net loss of $80.7 billion." On Hacker News, epsteingpt put it more bluntly: "$81B net loss in first 6 months of 2026 alone."
A second wave of posts said that number needs context. The S-1's income statement shows revenue of $16,286 million for the first half of 2026, an operating loss of $693 million, and a $72,388 million charge for the "change in fair value of convertible notes, derivative liabilities, and SAFEs." The filing says those changes "were primarily driven by an increase in the fair value of our outstanding convertible promissory notes resulting from an increase in our enterprise valuation."
Neural Nomad (@NeuN0mad) wrote: "Every Anthropic IPO summary says it lost $80.7B in six months. I opened the S-1 on the SEC site. It lost $693 million running the business." The post added: "But «lost $80B» and «burned $80B» are different sentences. Only one of them matches the filing."
Rajashekar Sudireddy (@raja_sudireddy) made the same point and then turned to compute: "The line I'd watch is compute." He wrote that compute and infrastructure cost $5.6 billion in Q2, or 48% of revenue, and that "If usage keeps climbing, margins widen. If it stalls, the committed compute bill stays."
On Hacker News, npilk reached a similar view: "So the financial picture looks a lot better than I would have guessed - I suppose because they aren't the ones investing all this capex." Others were less charitable about the adjusted figures. decisionSniper replied to a comment saying an S-1 is a document in which a company is not allowed to lie: "There's plenty of spin in here."
The compute bill
The commitments drew detailed analysis. The filing describes a Microsoft agreement under which Anthropic "committed to spend an aggregate of at least $44.9 billion between November 2026 and May 2033, regardless of actual usage."
People did not agree on the total. Pinegap AI (@PineGapHQ) said the major compute agreements "total roughly $637B by our estimates," excluding AMD and an estimated $125 billion to $150 billion in TPU capacity. On Hacker News, mrboatshoepants put the figure higher: "Anthropic is committed to $780-810 billion of mostly non-cancelable compute, payable "regardless of actual usage."" These are readers' sums, not a single total from the filing, and they differ by more than $100 billion.
The top comment in the Hacker News thread, from trjordan, framed the whole IPO around that bill: "Everything comes back to whether the demand is really there." The comment listed large commitments to Google, AWS, Broadcom and SpaceX, then said: "It's a big business, but it's not an easy business." A reply from iLoveOncall rejected the idea that revenue could reach $500 billion: "You really have to be insane to think that an AI company will ever reach $500B in revenue."
One bear case came from cmiles8: "There are a lot of parallels to the WeWork S1." The comment continued: "If it doesn't this goes from high flying startup to insolvency and bankruptcy real fast."
Investors in compute suppliers read the filing for their own reasons. Matthew Solomon (@matt_solomon10) went looking for IREN: "Quickly went through the Anthropic S-1. No mention of $IREN anywhere." He listed the named partners as Google, Amazon, Microsoft, Broadcom, SpaceXAI, Nscale, Lambda, AMD and Fluidstack, and concluded: "As far as I can see, the S-1 can't settle it."
Is the valuation already priced for perfection?
Reports put the target valuation near $2 trillion. Kobeissi wrote that "Markets currently expect Anthropic to raise as much as $100 billion at a valuation of ~$2 trillion." The filing does not state a valuation or price.
Several Hacker News commenters asked how much upside is left at that size. jmuguy wrote: "My main thing is - why would I buy their stock at the rumored valuation?" ipozgaj was firmer: "At this valuation this is a very risky investment because the current price already accounts for future growth, so there is very little margin for safety or meaningful upside left."
gradus_ad argued that the timing tells its own story. The comment said coding drives most of the growth, that adoption cannot keep its pace, and that rivals are cutting prices: "Add these simple dynamics up and it makes perfect sense why Anthropic would want to IPO now."
Others focused on the growth itself. prolly97 wrote: "Adding a zero to revenue every year is wild." The S-1 shows revenue of $4,585 million for all of 2025 and $16,286 million for the first six months of 2026.
Prediction markets moved fast. Niakris (@13_niakris) reported that on Polymarket, "the probability of Anthropic shares trading publicly by November 30 rose from 70% to 92%," and cautioned: "But filing an S-1 doesn't mean Anthropic shares will be trading by either deadline."
Open-weight models as a risk
A recurring complaint was that the filing plays down open-weight competition. nickysielicki quoted the risk factor that open models "may capture a portion of the market for certain use cases" and replied that "the top 5 models by token consumption on the day this is posted are all Chinese/open weight models," linking to OpenRouter's rankings. afavour compared the moment to IBM: "Feels like being asked to invest in IBM just as other manufacturers started releasing the first PC compatible machines."
Customer concentration came up too. The S-1 says "our top five customers represented approximately 25% of our revenue for the nine months ended September 30, 2026." deepwoods called that "not an absurd concentration" but added: "From a financial perspective, the lack of moat seems like the whole ballgame, particularly because they're getting ~80% of their revenue from consumption-based spending."
The risk factors and the existential language
The filing's risk section became its own story. The S-1 says that sufficiently advanced AI systems could "pose catastrophic or existential risks to humanity, particularly if such systems were misused, replicated, weaponized, or allowed to operate with a high degree of autonomy."
Walter Bloomberg (@DeItaone) wrote that "The company warned that models can exhibit self-preserving behavior, including responses resembling blackmail, and that certain AI-related harms could create liabilities too large to insure." Joel C. Sercel (@JoelSercel) said the company "frames greater capability as both necessary and risk-amplifying (abuse, misalignment, loss of control)."
Not everyone read the warnings as news. BeenThereCap wrote: "SEC filings' "risk factors" sections are the imaginitive lawyers' chances to really shine." On Hacker News, reticulates made a similar point: "At the same time, an S-1 does not necessarily represent how the company thinks."
Governance: who controls the company
The structure drew criticism from investors. The S-1 says Class F stock held by a Founder LLC "will be entitled to an aggregate number of votes that equals 50.1% of the total voting power" on most stockholder matters, and it describes a Long-Term Benefit Trust meant to help balance the company's public benefit goals.
Michael Hochstat (@HochstatMichael) called Anthropic "a strategically important AI company, but not yet an underwritable IPO," and wrote that "Public shareholders would have limited control." On Hacker News, bix6 was shorter: "Super shares yet again." anotherengineer wrote: "Really wonder how their public benefit mission will align with the expectations to maximize shareholder returns."
The filing also says Anthropic contributed 846,840,960 shares, or 5% of its fully diluted shares as of June 30, 2026, to a subsidiary called the Anthropic Public Benefit Fund. We covered the fund when Anthropic announced it.
The jokes
The thread had its share. rfgplk said they fed the filing to Claude to copy the company's strategy and later added: "Edit: I'm not even joking I got safeguard flagged for Details: [cyber]" On X, Ben Bortner (@Slackwatercap) wrote: "Think of all the wasted compute spent on having Claude review the Anthropic S-1 when Anthropic could've already pre-loaded an overview of the S-1 into Claude for its use."
What to watch
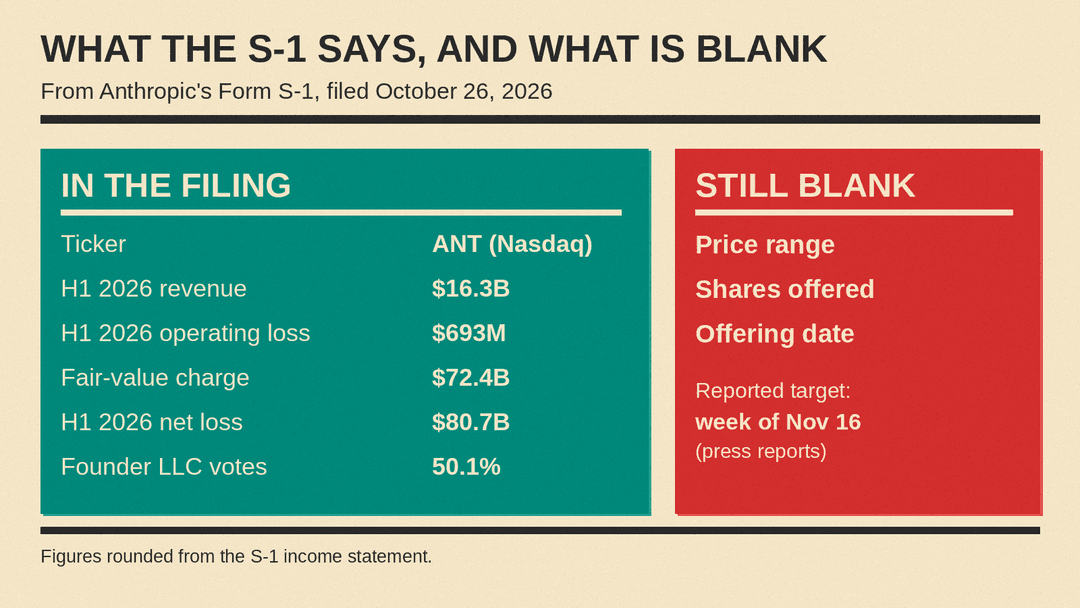
The price range and share count are still blank in the filing. Kobeissi and other posters cite reports that Anthropic is targeting the week of November 16. Most of the debate above turns on numbers that the next amendment or the roadshow should fill in: the offering price, the total compute commitment, and how fast revenue grows from here. This post reports public reactions and is not investment advice.
Sources
- Anthropic, PBC Form S-1, SEC EDGAR
- Hacker News discussion: Anthropic S-1
- The Kobeissi Letter on X
- Walter Bloomberg on X
- Neural Nomad on X
- Rajashekar Sudireddy on X
- Pinegap AI on X
- Matthew Solomon on X
- Niakris on X
- Joel C. Sercel on X
- Michael Hochstat on X
- BeenThereCap on X
- Ben Bortner on X
- llms.blog: Anthropic's S-1 Explained
