
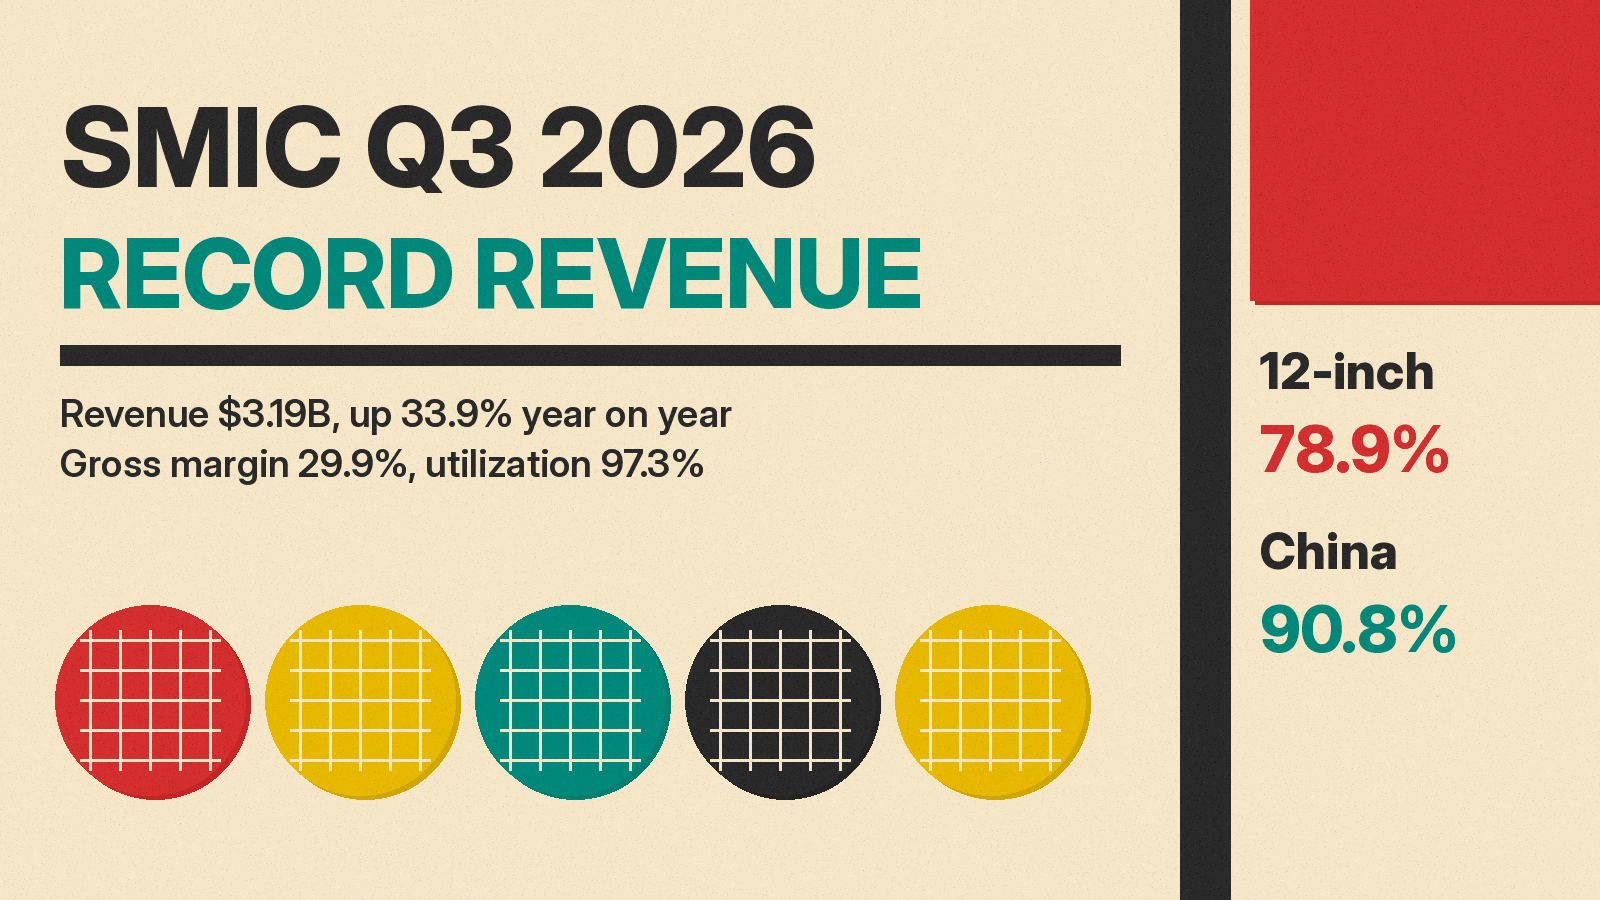
Semiconductor Manufacturing International Corporation (SMIC) reported revenue of $3,190.0 million for the three months ended September 30, 2026, up 6.1% from $3,005.6 million in the second quarter and up 33.9% from $2,381.8 million a year earlier. SMIC filed the unaudited results with the Hong Kong stock exchange on November 12, 2026.
The Standard reported that "strong domestic demand pushed revenue to a record high." The Wall Street Journal headlined its report "China's SMIC Doubles Profit, Posts Record Revenue on AI Spillover Effects."
SMIC Q3 2026 results: the key numbers
All figures are from SMIC's filing, in US dollars, under IFRS:
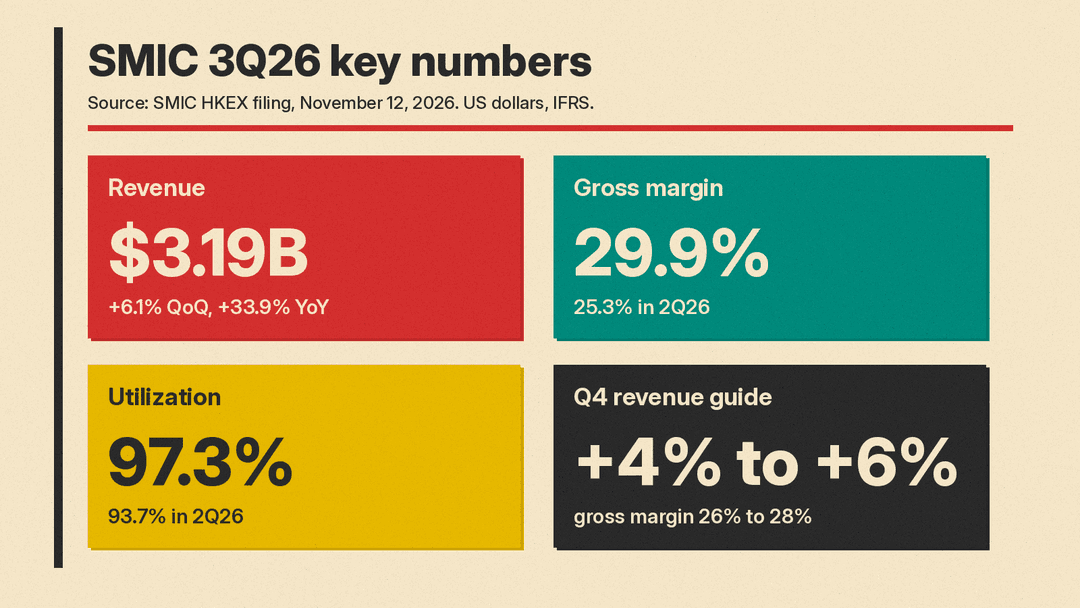
- Revenue: $3,190.0 million, up 6.1% quarter on quarter and 33.9% year on year.
- Gross profit: $953.2 million, up from $760.6 million in 2Q26 and $522.8 million in 3Q25.
- Gross margin: 29.9%, up from 25.3% in 2Q26 and 22.0% in 3Q25.
- Profit from operations: $710.1 million, up 32.9% quarter on quarter.
- Profit attributable to owners of the company: $428.4 million, up 123.4% from $191.8 million a year earlier, but down 10.6% from $479.2 million in 2Q26.
- Wafer shipments: 3,033,683 standard logic 8-inch equivalent wafers, up 5.7% quarter on quarter and 21.4% year on year.
- Utilization rate: 97.3%, up from 93.7% in 2Q26 and 95.8% in 3Q25.
- Capital expenditure: $1,094.3 million, down from $1,835.7 million in 2Q26.
Above its own guidance
In its second-quarter release on August 13, 2026, SMIC guided third-quarter revenue to "increase by 2% to 4% QoQ" and gross margin "to range from 26% to 28%." Actual revenue growth was 6.1%, and gross margin was 29.9%, above the top of both ranges.
The Wall Street Journal, as summarized by Techmeme, reported that net profit came in above an estimate of about $396.8 million.
SMIC gave two reasons in the filing. Revenue growth "was mainly due to the increase in wafer shipments in 3Q26." Gross margin rose "due to the increase in utilization rate and the product mix change in 3Q26."
Why profit fell from the second quarter
Operating profit rose, but profit attributable to owners fell from $479.2 million to $428.4 million. The filing shows "other income, net" swung from a $275.9 million gain in 2Q26 to a $32.1 million loss in 3Q26.
SMIC said the change in other gains and losses "was primarily caused by the fair value change in equity securities." It also said its share of profit from associates and a joint venture fell "due to the decreased gain on the investments in associates in 3Q26." Some of those associates are investment funds, according to the filing.
Where the revenue came from
More than 90% of SMIC's revenue came from China. By customer location, the filing shows:
- China: 90.8% of revenue, up from 90.2% in 2Q26 and 86.2% in 3Q25.
- America: 7.8%, down from 8.2% and 10.8%.
- Eurasia: 1.4%, down from 1.6% and 3.0%.
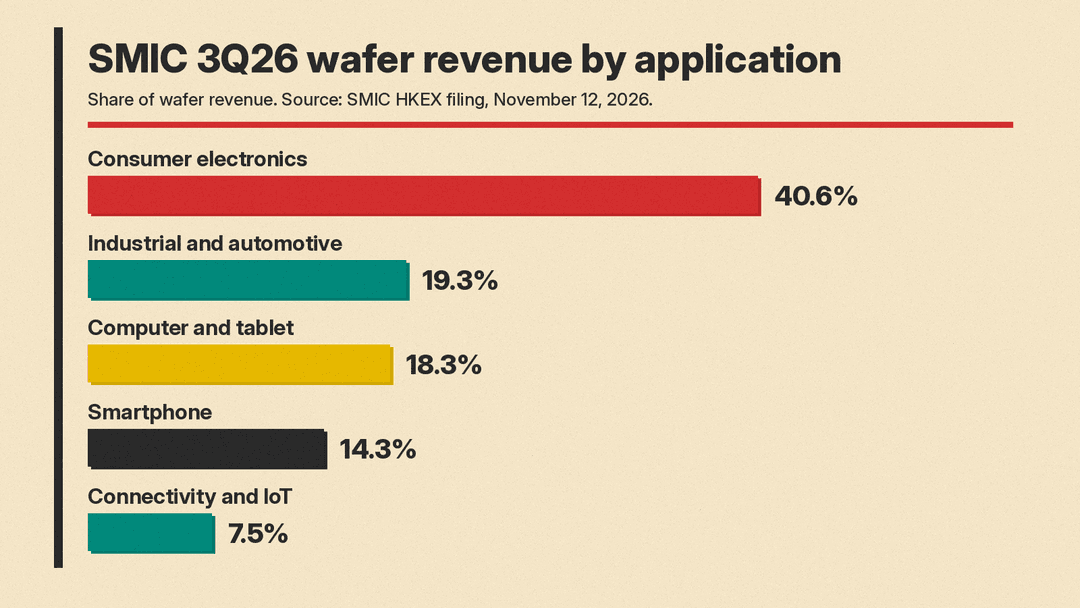
By application, wafer revenue split this way in 3Q26:
- Consumer electronics: 40.6% (44.2% in 2Q26).
- Industrial and automotive: 19.3% (16.5% in 2Q26, 11.9% in 3Q25).
- Computer and tablet: 18.3% (15.6% in 2Q26).
- Smartphone: 14.3% (16.9% in 2Q26, 21.5% in 3Q25).
- Connectivity and IoT: 7.5% (6.8% in 2Q26).
12-inch wafers made up 78.9% of wafer revenue, and 8-inch wafers 21.1%.
Capacity and spending
Monthly capacity rose to 1,116,750 standard logic 8-inch equivalent wafers in 3Q26, from 1,096,500 in 2Q26, according to the filing. Research and development expenses rose 23.9% quarter on quarter to $258.4 million, which SMIC said "was mainly due to the higher level of R&D activities in 3Q26."
Depreciation and amortisation was $1,270.4 million, up 4.8% from the second quarter and 27.6% from a year earlier. SMIC ended the quarter with $13.4 billion of total cash on hand and $14.9 billion of total debt.
Fourth-quarter guidance
SMIC said: "In the fourth quarter, the Company's revenue is expected to increase 4% to 6% sequentially, and the gross margin is expected to be in the range of 26% to 28%." The low end of that margin range is 3.9 percentage points below the 29.9% it just reported.
The company also said it "expands capacity in response to customer demand." SMIC will hold its earnings call on Friday, November 13, 2026, at 8:30 a.m., according to the filing. The filing does not give a time zone.
Why it matters for AI hardware
SMIC describes itself as "the front runner in manufacturing capability, manufacturing scale, and comprehensive service in the Chinese Mainland." In August, SMIC said that "the industrial momentum and spillover effects generated by AI will persist, driving broad based demand for integrated circuit manufacturing." The new filing does not use the word AI, so the exact share of AI-related demand in this quarter is not stated by SMIC.
For Taiwan's TSMC, see our report on TSMC's record October revenue. For another China chip story, see Alibaba's plan to spin off its T-Head chip unit in Hong Kong.
Sources
- SMIC: unaudited results for the three months ended September 30, 2026 (HKEX filing, November 12, 2026)
- SMIC: unaudited results for the three months ended June 30, 2026 (HKEX filing, August 13, 2026)
- The Standard: SMIC Q3 net profit surges 123pc to US$428.4m
- The Wall Street Journal: China's SMIC Doubles Profit, Posts Record Revenue on AI Spillover Effects
- Techmeme summary of the WSJ report
